How to Prepare for a Possible Interest Rate Rise in Australia
The Reserve Bank has already raised the cash rate three times in 2026, and another increase before year's end is possible. The best way to prepare is to stress-test your budget at a higher repayment, build a savings buffer, and review your loan now — before rates move, not after.
Uncertainty Makes It Hard to Plan
If you've got a mortgage, you've probably felt the impact of rate rises already this year. The hardest part is often the uncertainty — not knowing whether your repayments are about to increase again makes it difficult to plan your budget with any confidence.
Inflation has stayed above the Reserve Bank's target range for some time, and recent economic data — including employment and household spending figures — has come in stronger than expected. That combination means another rate rise before the end of the year genuinely can't be ruled out.
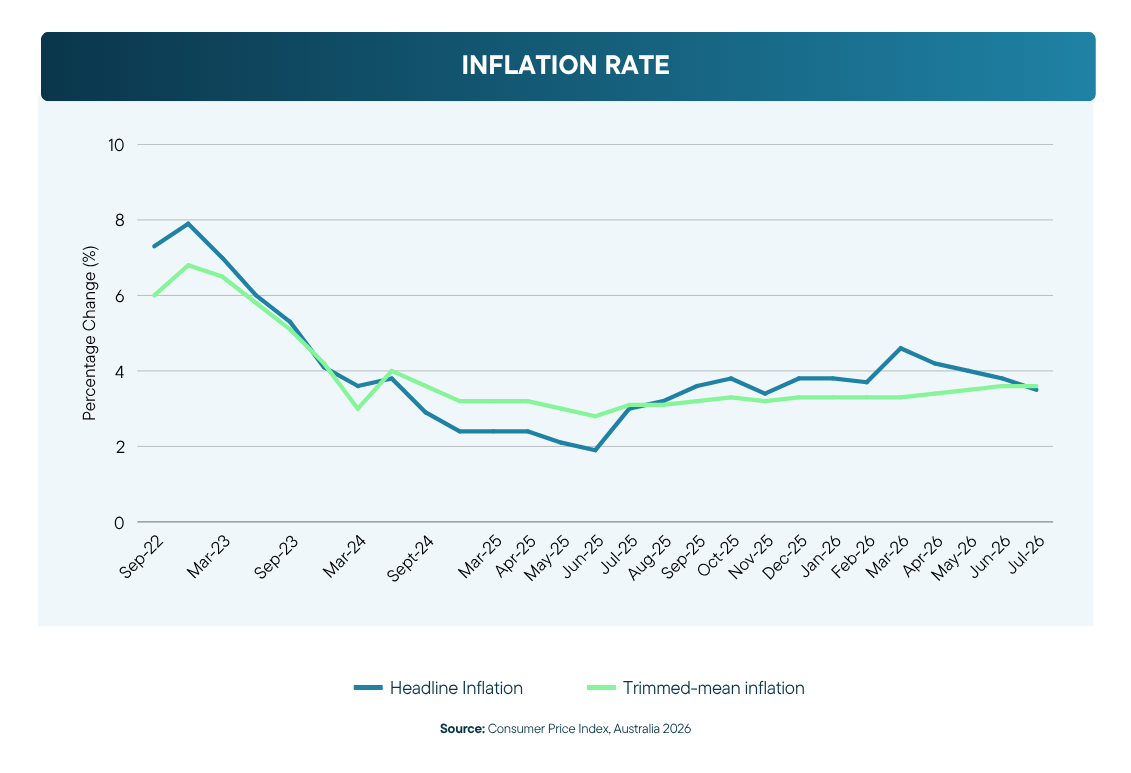
As the chart shows, both measures have come down a long way from their 2022 peak, but they've been sitting stubbornly around the 3.5–3.6% mark for months rather than continuing to fall toward the RBA's target. That's the exact pattern the Reserve Bank watches closely when deciding whether to raise rates again.
Many borrowers only react once a rate rise actually happens. By then, the higher repayment has already hit their account, with far less room to adjust.
Prepare Now, Before the Decision Is Made
Rather than waiting to see what the Reserve Bank decides, there's plenty you can do now:
Stress-test your budget. Work out what your repayments would look like if rates rose another 0.25% to 0.50%. If that feels tight, better to know now.
Build a bigger cash buffer. Even a modest emergency fund gives you breathing room if repayments increase.
Review your current rate. Rates vary significantly between lenders — if you haven't checked yours against the market in the past 12 months, it may no longer be competitive.
Use your offset or redraw facility. Parking extra funds there reduces the interest you're charged, cushioning the impact of any rate rise.
Trim discretionary spending now, on your own terms, rather than being forced into sudden cuts later.
If you're planning to buy, it's also worth calculating your repayments at a rate slightly above today's level before deciding what you can comfortably afford — rather than stretching to the maximum based on current rates alone.
Confidence, No Matter What the RBA Decides
Preparing in advance means a rate rise — if it happens — becomes a manageable adjustment rather than a financial shock. You'll know exactly where you stand, have a buffer to fall back on, and potentially already be on a more competitive rate than when you started.
And if the Reserve Bank holds rates steady instead? You're still better off, with a bigger buffer, a rate you know is competitive, and a clearer financial picture either way.
Frequently Asked Questions
Will interest rates go up again in Australia?
It's not guaranteed, but it's a real possibility. Inflation has stayed above the Reserve Bank's target range, and strong economic data has kept another rate rise on the table for upcoming meetings.
How much could my mortgage repayments increase?
It depends on your loan size. As a rough guide, a 0.25% increase on a $500,000 loan adds around $75–$80 a month — your mortgage broker can calculate your exact figure.
Should I fix my home loan rate?
It depends on your circumstances and how long you plan to stay in your current loan. A mortgage broker can talk you through the pros and cons of fixed, variable, and split-rate options for your situation.
Not sure how a rate rise would affect you? Get in touch and we'll stress-test your mortgage together, so you know exactly where you stand.
General advice warning: This article contains general information only and does not take into account your objectives, financial situation or needs. Before acting on it, consider whether it's appropriate for you and seek personalised advice. All loans are subject to lender credit assessment and approval, and terms, conditions, fees and charges apply.