Rental Yields Are Rising in Australia: What It Means for Property Investors
Rental yields across Australia have climbed to 3.8% — the highest since 2019 — as property prices fall and rents keep rising. That's good news for investors' cash flow, but yield is only one part of the equation, and it's worth understanding the rest before you buy.
Falling Prices Look Bad — But They're Not the Whole Story
Australia's median property price has dropped for five months straight, down 3.6% over that period. If you're a property investor — or thinking about becoming one — that headline alone might feel discouraging.
But here's what most headlines miss: rents have been climbing at the same time, up 5.7% over the past year nationally. Lower prices combined with higher rents means rental yields have hit their highest point since 2019.
The real problem isn't the falling prices. It's that many investors assume a strong yield automatically means a good investment, without checking whether the rest of the numbers actually stack up.
Understand the Yield, Then Look Past It
Rental yield is simply the annual rent a property earns, shown as a percentage of its value. When prices fall and rents rise together, yields naturally go up — which is exactly what's happening now, with the national gross rental yield sitting at 3.8%.
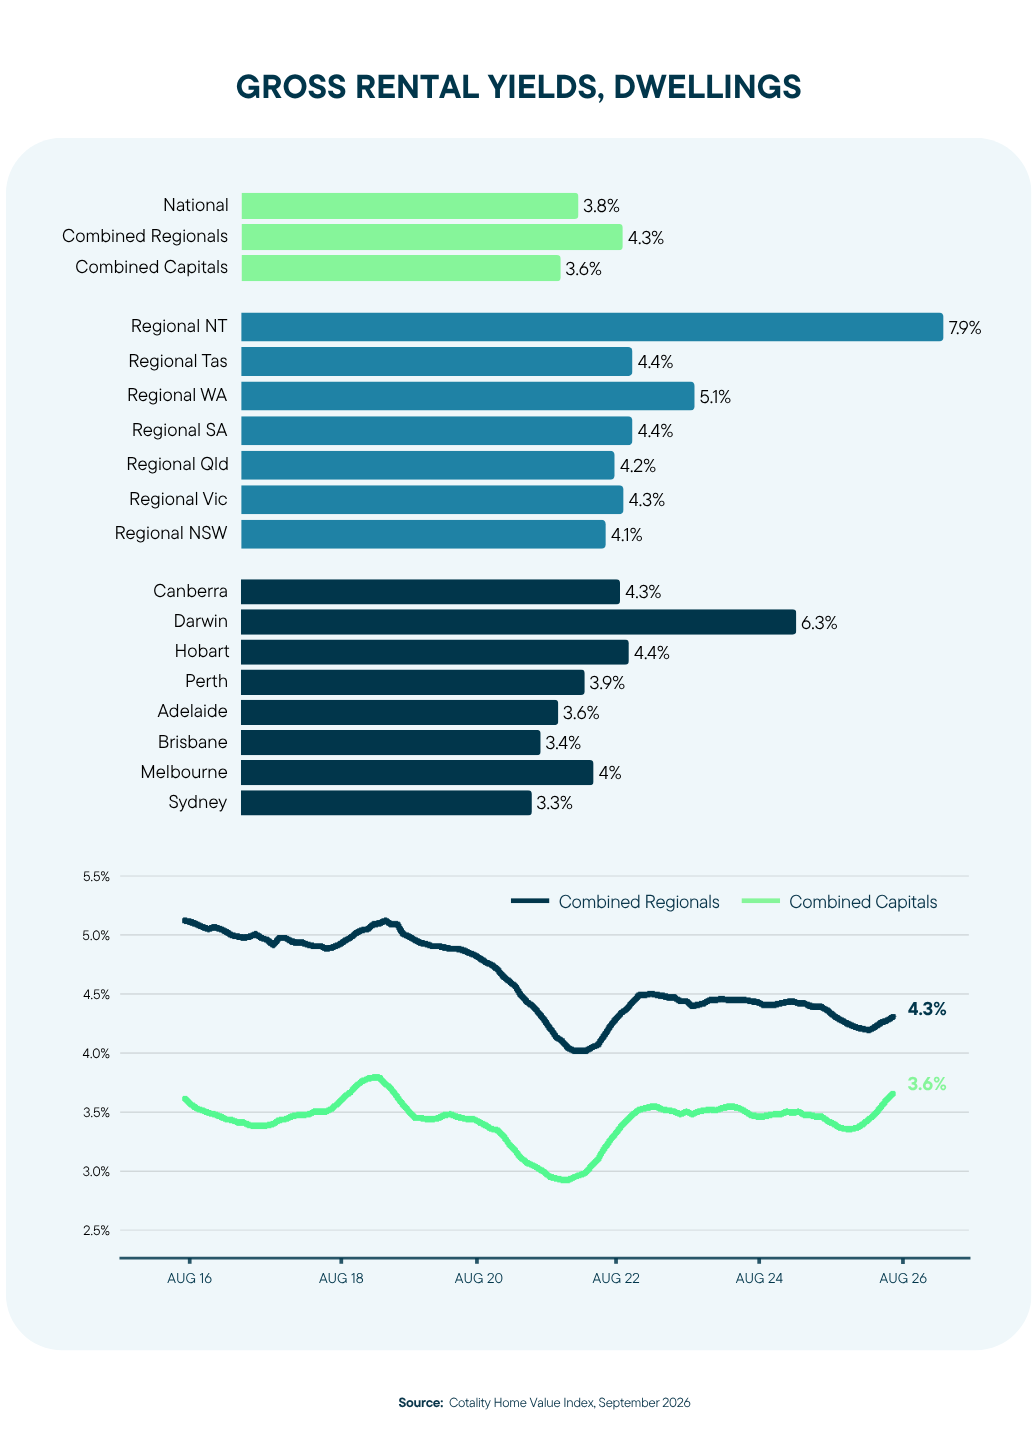
The gap between regions is significant too — Regional NT is currently the standout at 7.9%, while Sydney sits at the other end at 3.3%. Regional areas overall are outperforming the capitals (4.3% versus 3.6%), a pattern that's held fairly consistently over the past decade based on Cotality's tracking.
A higher yield can mean:
Stronger monthly cash flow
More breathing room to cover mortgage repayments
Less reliance on future price growth to make the investment worthwhile
But yield alone doesn't tell you if a property is a smart buy. Before committing, it's worth working through a few other numbers:
Loan repayments — what will they look like at current rates?
Property management costs — are you self-managing, or paying an agent?
Maintenance — older properties often cost more to keep in good condition
Vacancy risk — how in-demand is the area for tenants?
Capital growth potential — will the property likely grow in value over time too?
A high-yield property that ticks every one of these boxes is a genuinely strong opportunity. One that ignores them can quietly turn into a costly mistake down the track.
Smarter Buying, Stronger Cash Flow
Investors who look past the yield number — and structure their loan the right way — are in a much stronger position right now than those chasing yield alone. With rents rising and prices softer in many areas, well-researched purchases can deliver both strong cash flow and long-term growth.
The right loan structure matters just as much as the right property. Depending on your goals, that might mean an interest-only loan to maximise cash flow, an offset account to reduce interest costs, or a specific lender whose investment lending policy suits your circumstances.
Frequently Asked Questions
What is rental yield?
Rental yield is the annual rent a property earns, expressed as a percentage of its purchase price or value. A property earning $26,000 a year in rent, valued at $650,000, has a gross rental yield of 4%.
Is now a good time to buy an investment property in Australia?
The current numbers — falling prices and rising rents — favour investors more than they have in several years. That said, it still depends on your borrowing capacity, goals, and the specific property and location.
How do I calculate rental yield?
Divide the property's annual rental income by its purchase price, then multiply by 100 for the gross yield. Subtract ongoing costs like management fees and maintenance for a more accurate net yield.
Thinking about buying an investment property? Get in touch and we'll help you work out your borrowing capacity and the loan structure that suits your goals.
General advice warning: This article contains general information only and does not take into account your objectives, financial situation or needs. Before acting on it, consider whether it's appropriate for you and seek personalised advice. All loans are subject to lender credit assessment and approval, and terms, conditions, fees and charges apply.